

Flexible Car Finance VS Fixed PCP: Which Suits You Best?

Choosing the right car finance option is critical for both budget management and long-term satisfaction. This article compares Flexible Car Finance and Fixed PCP, focusing on their structures, costs, and user experiences in the UK market. It aims to help you understand which finance solution aligns best with your financial goals, driving habits, and future plans, enabling an informed decision for your next vehicle.
Exterior Design
As financial products, neither Flexible Car Finance nor Fixed PCP directly influences the physical attributes of the vehicle you acquire. Both methods provide access to a diverse range of vehicles, from compact city cars to luxury SUVs, according to your budget and preferences. The choice of finance does not limit the exterior design, colour, or specification of your selected vehicle. Nevertheless, Flexible Car Finance may grant greater freedom to change vehicles more frequently, enabling you to experience a variety of exterior designs over time. In contrast, Fixed PCP agreements typically commit you to a specific vehicle for the contract duration, unless you opt to upgrade at the end of the term.
Interior Design
Likewise, the interior design of your chosen vehicle remains unaffected by the finance method. Both Flexible Car Finance and Fixed PCP offer access to vehicles across all trim levels and interior configurations, subject to credit approval and budgetary limits. Flexible Car Finance may offer increased adaptability if you wish to upgrade or change vehicles mid-term, allowing you to experience different interior layouts and technologies. Fixed PCP, on the other hand, generally ties you to your selected vehicle until the agreement concludes, unless you settle early or part-exchange.
Engine and Performance
Neither Flexible Car Finance nor Fixed PCP restricts your choice of engine type or performance specification. Whether your preference is for petrol, diesel, hybrid, or fully electric powertrains, both finance options can be tailored to suit your requirements. Flexible Car Finance can be particularly beneficial for those anticipating changes in performance needs, as it allows for the possibility of switching to a different vehicle or specification during the contract. Fixed PCP is more rigid, with performance options determined at the outset and fixed for the duration of the agreement, unless you choose to upgrade at the end.
Fuel Consumption and Efficiency
The finance product itself does not affect the fuel consumption or efficiency of your vehicle. However, Flexible Car Finance can enable more frequent vehicle changes, which may allow you to take advantage of evolving fuel efficiency technologies or adapt to changing personal requirements, such as transitioning to an electric vehicle. Fixed PCP generally involves a longer commitment to a single vehicle, so it is important to consider future fuel costs and efficiency when making your initial selection.
Price
In the UK, the cost structures of Flexible Car Finance and Fixed PCP differ considerably. Flexible Car Finance may involve variable interest rates, flexible payment schedules, and the option for early settlement with minimal penalties. This can result in fluctuating monthly payments, depending on market conditions and the terms agreed. Fixed PCP, by contrast, offers set monthly payments over a fixed term (typically 24 to 48 months), with a predetermined balloon payment should you wish to purchase the vehicle at the end. PCP agreements often require an initial deposit (usually 10% of the vehicle price), followed by fixed payments, which can make budgeting more straightforward. However, total costs may be higher if you decide to purchase the vehicle outright, due to the final balloon payment. Flexible Car Finance may offer lower overall costs for those who do not intend to keep the car long-term or who wish to settle the agreement early.
Driving Experience
From a user perspective, Flexible Car Finance provides greater adaptability, allowing you to modify your agreement if your circumstances change. This may include adjusting payment terms, changing vehicles, or settling early without significant penalties. Such flexibility can be particularly advantageous for drivers with uncertain or variable needs. Fixed PCP, conversely, offers a stable and predictable structure, ideal for those who value consistency and intend to use the vehicle for the full contract term. However, PCP agreements often come with strict mileage limits and wear-and-tear clauses, which can result in additional charges if exceeded.
Customer Reviews and Ratings
Customer feedback in the UK highlights that Flexible Car Finance is highly regarded for its adaptability and customer-focused approach, especially among those experiencing changing personal or professional circumstances. Users appreciate the ability to adjust terms or change vehicles without incurring major penalties. However, some note that variable interest rates can introduce unpredictability in payments. Fixed PCP receives positive reviews for its simplicity, transparency, and ease of budgeting, particularly for those who prefer a clear, fixed payment schedule. Negative feedback often centres on the lack of flexibility, high final payments, and strict contract conditions.
Final verdict: Flexible Car Finance or Fixed PCP?
For most users seeking adaptability and the ability to respond to changing circumstances, Flexible Car Finance offers superior flexibility and control over vehicle choice and payment structure. However, if you prioritise predictable monthly payments and plan to use the vehicle for a set period, Fixed PCP provides clarity and financial stability. Ultimately, the best option depends on your individual requirements and future plans. For tailored advice and to explore which finance solution best matches your needs, visit your local sandicliffe dealership for our expert advice.




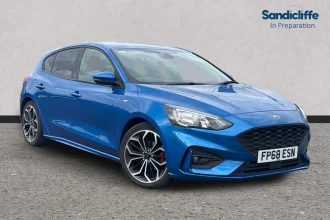
Ford Focus
Focus 1.0 L EcoBoost ST-Line X 5dr 6Spd 125PS
- 2018
- 25,932 miles
- Petrol
- Manual
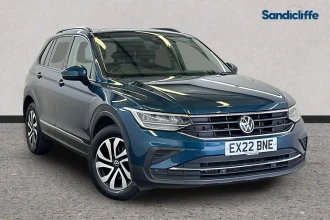
Volkswagen Tiguan
Tiguan 1.5 TSI 150 Active 5dr DSG Estate
- 2022
- 29,889 miles
- Petrol
- Automatic


