FCA Car Finance Investigation: What UK drivers need to know
What does the FCA car finance investigation mean for UK drivers in 2026? The FCA’s probe into motor finance means millions of UK drivers could be owed compensation for past unfair commission practices. With a new redress scheme in place, understanding eligibility, timelines and how to claim is crucial for anyone who took out a car loan between 2007 and 2024.
The FCA car finance investigation has shaken up the UK motor finance world. With a new redress scheme now active, drivers who used car loans or finance deals could be owed money. This guide breaks down what the FCA probe means, who is affected, how to claim compensation, and what changes to expect in the future.
What is the FCA investigation into car finance?
Background from the FOS ruling
The FCA launched its sector-wide investigation in January 2024 after the Financial Ombudsman Service ruled that some lenders allowed brokers, like car dealerships, to adjust interest rates on motor finance deals. This practice, known as discretionary commission arrangements, let brokers increase rates to earn higher commission. It often led to drivers paying more than necessary.
Key findings
About 40% of car loans before 2021 involved these hidden commissions. The FCA banned such arrangements in January 2021, but the investigation revealed that many consumers were still affected by older agreements. The focus is now on making the market fairer and more transparent for everyone.
Which motor finance deals are in scope?
Date range and eligibility
The FCA’s review covers motor finance agreements taken out between 6 April 2007 and 1 November 2024. If you signed a car loan, Personal Contract Purchase (PCP), or Hire Purchase (HP) deal during this period, you may be eligible for compensation if your agreement included an undisclosed or excessive commission.
Estimated scale of affected deals
It is estimated that around 12.1 million agreements could be affected. This means millions of drivers across the UK may have overpaid and could now benefit from the redress scheme.
What does the motor finance redress scheme mean for consumers?
Compensation estimates
The FCA expects firms to pay out around £7.5 billion to consumers, with an average payout of about £830 per person. Here is a simple breakdown:
Total bill for firms | Estimated consumer share | Average compensation per consumer |
£9.1 billion | £7.5 billion | £830 |
How to claim directly
To claim compensation:
- Check if your finance agreement falls within the eligible dates.
- Contact your lender directly. You do not need to use a claims management company.
- Provide details of your agreement and any supporting documents.
- Wait for your lender’s response. The FCA has asked firms to make the process as simple as possible.
Avoid using claims management companies, as they may charge high fees for something you can do yourself.
When will affected consumers receive compensation?
Official timeline
- 31 March 2026: Redress scheme officially launched.
- 30 June 2026: Deadline for firms to process claims for agreements from 1 April 2014 onwards.
- 31 August 2026: Deadline for agreements from 6 April 2007 to 31 March 2014.
- Late 2026/early 2027: First compensation payouts expected, but may be delayed.
Legal challenges and likely delays
Several lenders are contesting aspects of the scheme in court. These legal battles could delay compensation pay outs. The FCA is defending the scheme, but drivers should be prepared for possible setbacks.
How will dealerships be affected operationally?
Financial impacts
Dealerships and lenders have had to set aside large sums to cover compensation. This financial pressure may affect how some businesses operate in the short term, especially smaller dealerships.
Changes to sales and training
Dealerships must now:
Train staff on ethical selling and clear commission disclosure.
Review and update all finance sales processes.
Provide customers with clear, honest information about finance options.
Monitor compliance with new FCA guidelines.
By taking these steps, dealerships can rebuild trust and avoid future issues.

What does this mean for the future of car finance?
Market forecasts
Despite the investigation, the motor finance market is expected to grow to over £48 billion by 2026. However, many drivers remain cautious, with more than half saying they are less likely to use car finance after recent scandals.
EV finance implications
As electric vehicles become more popular, dealerships must offer transparent, flexible finance options for these cars. This shift is a chance to build trust with customers by being upfront about all costs and commissions.
Moving Forward with Confidence in Motor Finance
The FCA’s investigation is a big step towards fairness in the UK motor finance market. By tackling hidden commissions, the redress scheme gives drivers a real chance to get back what they are owed.
Dealerships are changing how they operate, focusing on transparency and customer trust. This is good news for anyone thinking about a new or used car, especially with the growing interest in electric vehicles.
If you want a stress-free, honest car buying experience, visit Sandicliffe’s online store. You will find clear information, fair finance options, and a team ready to help you every step of the way.
Frequently Asked Questions
Who is eligible for the redress scheme? Anyone who took out a motor finance agreement (PCP or HP) between 6 April 2007 and 1 November 2024 that included an undisclosed or excessive commission may be eligible.
How much could I get back? The average pay out is expected to be about £830, but your amount will depend on your agreement and how much extra interest you paid.
How do I claim compensation? Contact your lender directly with details of your finance agreement. You do not need to use a claims management company.
Will legal challenges delay payments? Yes, ongoing legal cases may delay compensation pay outs. The FCA is working to resolve these as quickly as possible.
How will this affect new car finance deals? New deals must now be fully transparent, with all commissions clearly disclosed. This should make future agreements fairer for consumers.
Should I use a claims management company? No, you can claim directly from your lender for free. Claims management companies may take a large portion of your compensation.
Approved Used Vehicles at Sandicliffe

Ford Puma
Puma Gen-E Premium 5 Door 46.8 kWh Standard Range 1 Speed Automatic
- 2026
- 1,395 miles
- Electric
- Automatic

Ford Kuga
Kuga ST-Line X 5 door 2.5L Duratec PHEV 243PS FWD CVT Automatic
- 2026
- 1,634 miles
- Automatic
Kia Stonic
Stonic 1.0T GDi 99 2 5dr Estate
- 2023
- 32,888 miles
- Petrol
- Manual
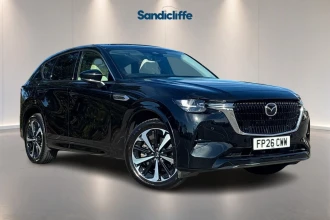
Mazda CX-60
Cx-60 2.5 PHEV Takumi Plus 5dr Auto Estate
- 2026
- 7,001 miles
- Automatic
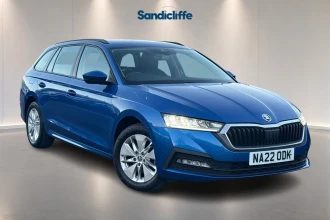
Skoda Octavia
Octavia 1.0 TSI e-TEC SE 5dr DSG Estate
- 2022
- 53,404 miles
- Petrol
- Automatic
Latest New Car Offers