

Car Finance with a Guarantor: How It Works and Who Can Apply

How can a guarantor help you get car finance if you have limited credit? A guarantor can increase your chances of approval by offering extra security to lenders. If you have little or poor credit, a guarantor’s support may open the door to car finance, helping you get on the road sooner. Read on to see how this works in real life.
Car finance with guarantor is a helpful solution for people who might struggle to get a car loan on their own. Whether you are new to borrowing or have a limited credit history, having someone back your application can make a real difference. In this guide, we explain how guarantor car finance works, who it suits, what is expected from a guarantor, and what alternatives you could consider. We also share practical tips and real-life examples to help you make the best choice for your circumstances.
Expert Opinion: Guarantor-backed car loans remain a practical route for many UK drivers, especially those who are just starting out or have faced financial bumps in the past. In my experience, a well-chosen guarantor can make all the difference, but both parties must understand the commitment. At Sandicliffe, we always advise customers to talk openly and review all responsibilities before signing. We see young drivers, self-employed people, and those rebuilding their credit benefit most from this option. With clear guidance and the right support, guarantor car finance can be a stepping stone to car ownership and better credit for the future.
What is guarantor car finance?
Understanding the concept
A guarantor car loan is a type of vehicle finance where a second person agrees to pay if the main borrower cannot. This extra layer of security reassures lenders, so they are more likely to approve your application. It is often used by people who have little or no credit history, or who have struggled with credit in the past.
Why this matters
Having a guarantor can help you get approved for a car loan when you might otherwise be turned down. For example, a young driver buying their first car with help from a parent as guarantor can get on the road much sooner. It can also help you build your own credit record for the future.
Recent trends in the UK
While not as common as other types of car finance, guarantor-secured auto loans remain popular with first-time buyers and those with weaker credit. According to recent UK figures, the value of new car finance business rose by 3% in early 2026, showing steady demand for flexible options like this.
Synonyms you may see for this finance type:
- guarantor-backed car loan
- car loan with guarantor
- vehicle finance with guarantor
- third-party car finance
- guarantor-secured auto loan
- guarantor-backed vehicle finance
Who needs car finance with guarantor?
Young drivers
If you are under 25 or just starting out, you may not have built up a credit history yet. A guarantor can help you get approved for your first car loan, whether you are buying a small hatchback for city driving or a used car for university runs.
Those with limited credit
If you have a thin credit file or some past financial issues, lenders may be cautious. A guarantor-backed vehicle finance agreement can give you another chance. For example, someone who had a missed payment a few years ago can still get a car loan with a trusted guarantor.
Self-employed borrowers
Being self-employed can make borrowing harder, as income can vary. If you run a small business or work freelance, a guarantor can help you secure finance for a work van or car, even if your accounts are less than three years old.

Who can act as a guarantor for a car loan?
Basic eligibility
A guarantor must usually be at least 21 years old (sometimes 25), live in the UK, and have a good credit history. They should not be financially linked to you, such as a spouse or joint account holder.
Income and credit requirements
Guarantors must show a stable income, often at least £20,000 a year—and have no recent defaults or missed payments. Lenders may prefer homeowners, but this is not always essential.
Family vs friends
Most guarantors are parents, siblings, or close friends. For example, a parent might help their child get their first car, or a friend could support someone rebuilding their credit. It is important that the guarantor is comfortable with the commitment.
Quick eligibility checklist for guarantors:
- Age 21 or over (some lenders may require 25+)
- UK resident
- Good credit history
- Stable income (check lender’s minimum)
- Not financially linked to borrower
How does car finance with guarantor work?
Application steps
Choose your car and check the finance amount needed.
Find a suitable guarantor who meets the criteria.
Both you and your guarantor complete the application.
Provide documents (see checklist below).
The lender checks both your details and your guarantor’s.
If approved, both sign the agreement, and you can collect your car.
Timelines and paperwork
Most applications are processed within 24 to 72 hours if all documents are ready. You will need:
- Proof of ID (passport or driving licence)
- Proof of address (utility bill or bank statement)
- Payslips or bank statements (for both borrower and guarantor)
- Proof of income
Legal obligations
Once the agreement is signed, the guarantor is legally responsible for any missed payments. If you miss a payment, the lender will contact your guarantor to pay instead. Both parties should understand this before agreeing.
Borrower’s checklist:
- Check your credit report
- Calculate how much you can afford monthly
- Ask your guarantor if they are comfortable with the risks
- Gather all required documents
Guarantor’s checklist:
- Review your own finances and credit history
- Ask questions about the loan amount and term
- Understand your legal responsibility
- Keep copies of all paperwork
What risks and responsibilities do guarantors face?
Credit impact
If the borrower misses payments, the guarantor must pay instead. Missed payments can harm the guarantor’s credit score and may affect their ability to borrow in the future.
Real-life examples
Imagine a parent guarantees a £10,000 loan for their child’s first car. If the child loses their job and cannot pay, the parent must step in. In another case, a self-employed friend guarantees a van for a business partner. If the business struggles, the guarantor could be left with the debt.
How to protect yourself
- Only agree if you trust the borrower
- Make sure you can afford to pay if needed
- Keep communication open throughout the loan
- Ask the lender about early warning if payments are missed
Quick tip for advisers:
At Sandicliffe, we always encourage open conversations about risks before anyone signs.
What alternatives exist to guarantor car finance?
Joint finance
You can apply for a joint car loan, where both parties share responsibility. This works well for couples or business partners.
Larger deposit
Putting down a bigger deposit (for example, £2,000 or more) can reduce the amount you need to borrow and improve your chances of approval.
Improving credit first
If you can wait, working on your credit score can help you qualify for a standard car loan. Paying bills on time and reducing debts are good first steps.
Comparison table
Option | Who it suits | Typical deposit (£) | Key risk to guarantor |
Guarantor car loan | Young drivers, poor credit | £0–£1,000 | Full legal responsibility |
Joint finance | Couples, business partners | £500–£2,000 | Shared responsibility |
Standard car loan | Good credit, stable income | £1,000+ | None |
Ready to explore your car finance options?
Car finance with a guarantor can open doors for drivers who might otherwise struggle to get approval. It is important for both borrowers and guarantors to understand the commitment and talk honestly before moving forward.
If you are looking for a car and want friendly, expert advice, visit Sandicliffe’s online store. We offer a wide range of vehicles and easy finance solutions to help you get on the road with confidence.
Frequently Asked Questions
What is car finance with guarantor? It is a car loan where a second person agrees to cover payments if the borrower fails to pay.
Who can be a guarantor? Usually someone over 21, a UK resident, with a good credit history and steady income.
How long does approval take? Many lenders can decide within 24–72 hours, depending on checks.
How does a guarantor affect credit? Missed payments can hit the guarantor’s credit record and finances.
What are simple alternatives? Joint finance, bigger deposit in pounds, or improving your credit before applying.
What documents do guarantors need to provide? Proof of ID, proof of address, recent payslips or bank statements, and proof of income.
Latest New Car Finance Offers




Fresh Into Stock Vehicles

Peugeot 2008
2008 1.2 PureTech Active 5dr Estate
- 2023
- 23,966 miles
- Petrol
- Manual
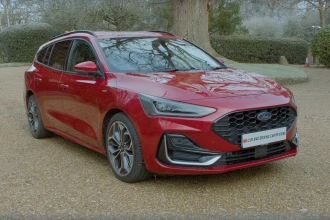
Ford Focus
Focus Titanium Estate 1.0L EcoBoost 155PS mHEV FWD 7 Speed PowerShift
- 2023
- 16,121 miles
- Petrol
- Automatic

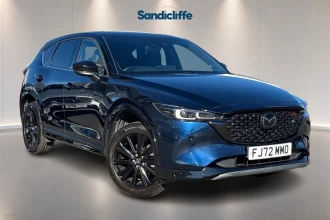
Mazda CX-5
Cx-5 2.0 Sport Black 5dr Estate
- 2022
- 64,000 miles
- Petrol
- Manual
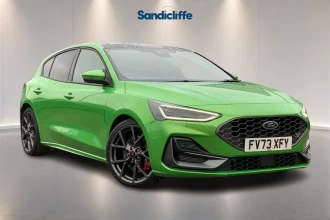
Ford Focus
Focus ST 5 door 2.3L EcoBoost 280PS FWD 7 Speed Automatic
- 2023
- 26,737 miles
- Petrol
- Automatic


